
Paper Mandate has not been able to post our regular daily portfolio note recently. Such is life. Today we’ve had the opportunity to sit down and assess how the portfolio went for August 2026. Better late than never.
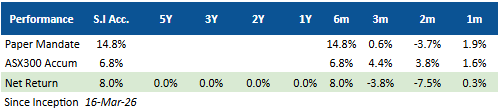
August was a positive month as the portfolio return +1.92% while the S&P/ASX 300 Accumulation Index posted a gain of +1.62%. This resulting in a relative outperformance of +0.30% for the month.
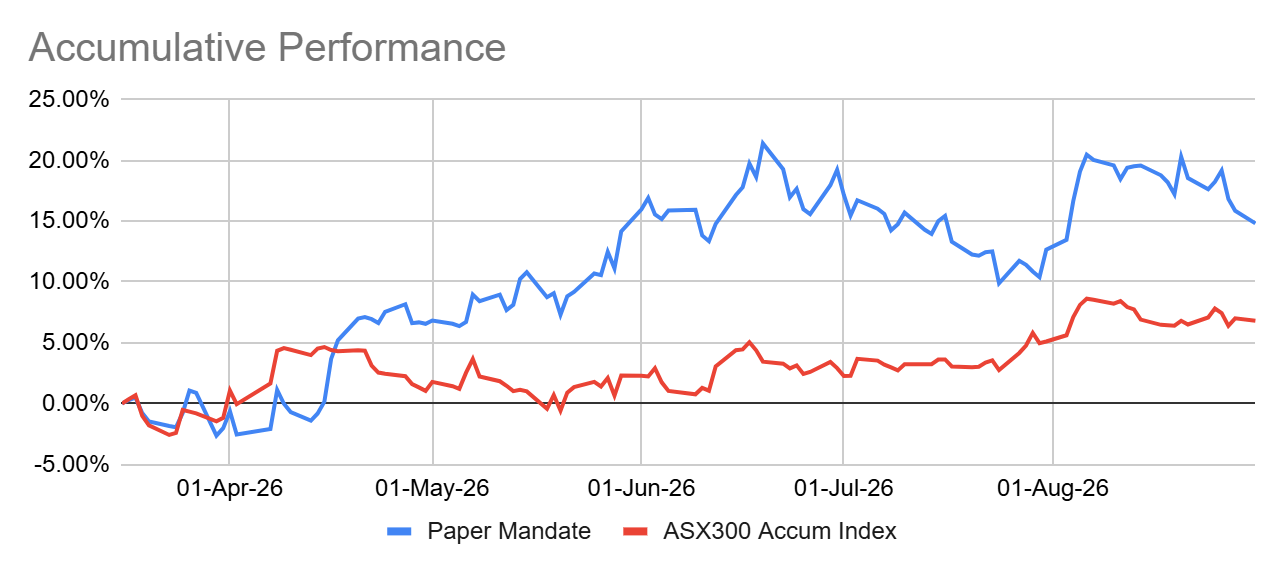
Our track record since inception is still outperforming the Benchmark with an accumulative return of 14.8% versus 6.8%, a +8.0% net outperformance.
The initial uplift at the start of the month was driven by strong rallies in SKS, BVS, 360, OBM, ZIP, and PC2. This was due by reporting season results.
Portfolio Attribution
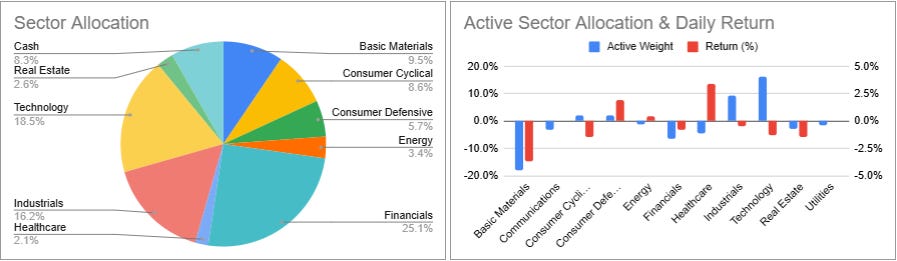
The portfolio’s monthly return was driven primarily by stock selection (+2.90%), while sector allocation (-1.31%) was a headwind. Interestingly, there was a negative contributor by interaction effects (-1.30%). This was driven by a -1.1% interaction effect for our Technology exposure.
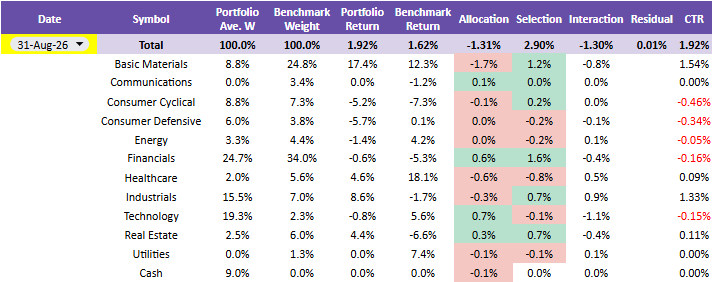
We were overweight the sector (+19.3% vs 2.3%) which drove a positive Allocation Effect (+0.7%), however the particular portfolio stocks did not perform as well as the benchmark subsector. This caused a negative Selection and Interaction Effect.
Materials stocks were the best positive contributors to performance (+1.54%), driven by OBM and PC2 (our gold exposure). Interaction Effect suggests that we could have upweighted the stocks, given our significant underweight vs the benchmark.
Interestingly, Financials contributed meaningfully to the Selection Effect (+1.6%) despite a negative contribution to overall performance (-0.16%). While the Benchmark sector fell -5.3%, our Financials were relatively more defensive (-0.6%). The only significant underperforming being GDG (-22.6%) for the month.
Pleasingly, the Residual in the Attribution table was negligible, +0.01%.
Key Contributors & Detractors
The NAV decreased -5.52% during July. The specific positions that drove the return by contribution were:
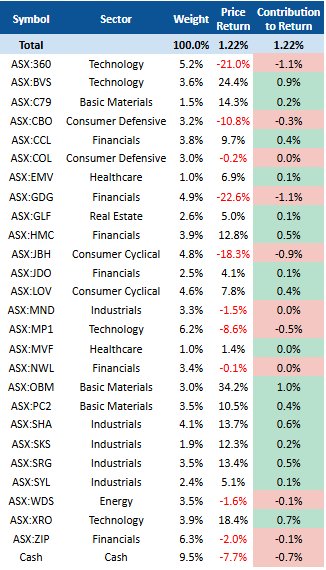
Ora Banda (OBM): Rose +34.2% and contributing +1.0% to total return
Bravura (BVS): Up +24.4%, adding +0.9% to portfolio return.
Xero (XRO): Advanced +18.4%, contributing +0.7%.
Key detractors were:
Generation Development (GDG): Fell -22.6%, detracting -1.1%
Life360 (360): Dropped -21.0%, detracting -1.1% to total return.
JB Hifi (JBH): Declined -18.3%, detracting -0.9% from total return
Portfolio Characteristics & Risk Metrics
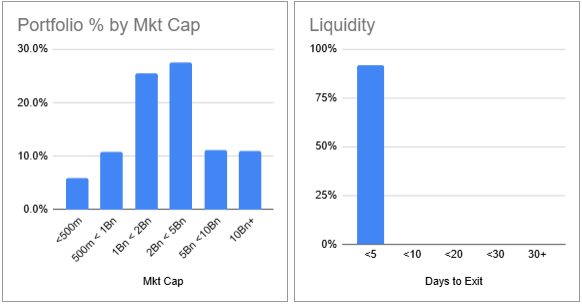
The current profile favours the mid-cap sweet spot, with the majority of companies between $1Bn to $5Bn in market cap. We have decreased our $2bn to $5bn bucket since last month.
The portfolio liquidity remains the same. Considering a 30% Average Daily Volume (ADV), the portfolio has a Days to Exit of 5 days. This is due to the small FUM size.
Other statistics include:
Weighted Avg Mkt Cap: $5,631m, higher than last month again.
WA Beta (1Y): 1.20, up from 1.19 indicating a more sensitive portfolio.
WA P/E Ratio: 31.8x, up from last month
Our Beta sensitivity is a concern as this will make the performance of the portfolio swing session to session. The largest beta contributing stocks are: 360, JDO, LOV, and NWL. All with 1Y Beta above 2 (according to Trading View).
The largest contributor to the Weighted Average PE is C79, with a current PE of 450x. This is last twelve months EPS mind you. Forward estimates make the PE much lower, 72x.
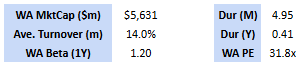
At the end of the month, the largest overweight is still Technology (+16.1% ) while Materials continues to be the largest underweight (-18.0%).
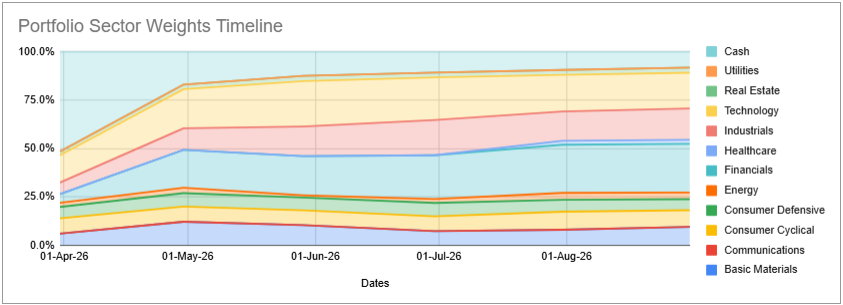
There were no large wholesale changes to the portfolio. We bought 1% more of GDG before month-end, after the price fell.
Outlook & Strategy
This was a positive month despite not changing the portfolio almost at all. The portfolio has generated a 14.8% absolute return since inception.
The AI theme and sentiment remains cautious. At time of writing, and since 31 August 2026, we trimmed our exposure to MP1. It is likely further trims to Technology are on the cards. The war in Iran, higher input costs, stick inflation, and interest rate rises are a drag for equities. Being fully invested may be a risk to the portfolio.
The focus for the coming months (as September is nearly over) will be to strategically take profits, and keep some dry powder due to the higher equity risk. Continue trimming successful Tech and AI stocks like MP1. Plus we definitely need to reduce our high beta exposure.
Disclaimer: This is a paper portfolio. Content is for educational purposes only and does not constitute financial advice. Always do your own research.