
Fund Status:
Portfolio Val: $1,078,723
Performance: Portfolio -0.12% | Benchmark -0.34%
Cash: $106,576
Bought/Sold None
Overnight Markets
Markets rebounded overnight with the Nasdaq and S&P500 up 1.11% and 0.41% respectively. Consumer Discretionary (+2.73%) and Tech (+1.119%) were the leaders while Utilities (-1.97%) and Real Estate (-1.17%) lagged. Oil continues to trend higher ($103) as tensions in the Middle East continue while Gold is holding relatively flat. Gold miners appear to be lagging the spot price, based on the performance of the GDX ETF. Reporting season is starting up with analysts are expecting 29% growth in profits for the S&P500

Australian Market
The ASX 200 finished down (-0.33%) with Consumer Staples (+1.14%), and Health Care (+0.87%) leading while Energy (-1.31%) and Materials (-1.16%) lagged. BHP (-1.6%) dragged the index after releasing their September quarter production figures. They had a 19% y/y drop in copper production. Meanwhile Cochlear (+5.2%) & Telix (+2.3%) rallied along with Healthcare. NextDC went into a trading halt as questions about their energy supply to the DC become a material concern to earnings.
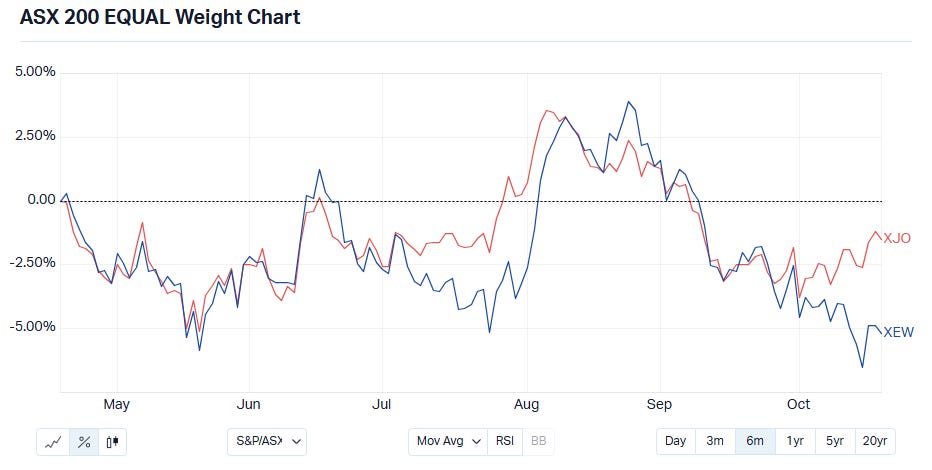
We are starting to see the market narrow as the ASX200 Market cap weight outperforming the ASX200 equal weight. This means the largest parts of the market are leading the way.
Portfolio Commentary
The portfolio fell -0.12%, outperforming the ASX 300 benchmark (-0.34%). We saw rallies PC2 (+4.14%), GDG (+3.28%), Coles (+1.85%), Life360 (+1.77%), C79 (+1.70%), Xero (+1.69%), and JB Hi-Fi (+1.50%). An interesting mix of staples, tech, discretionary and financials. These absorbed headwinds from MP1 (-3.26%), SKS (-3.20%), Zip (-2.30%), and Ora Banda (-1.81%).
Investment Activity
None
Disclaimer: This is a paper portfolio. Content is for educational purposes only and does not constitute financial advice. Always do your own research.