
Fund Status:
Portfolio Val: $1,091,645
Performance : Portfolio -0.42% | Benchmark -0.64%
Cash: $106,576
Bought/Sold None
Overnight Markets
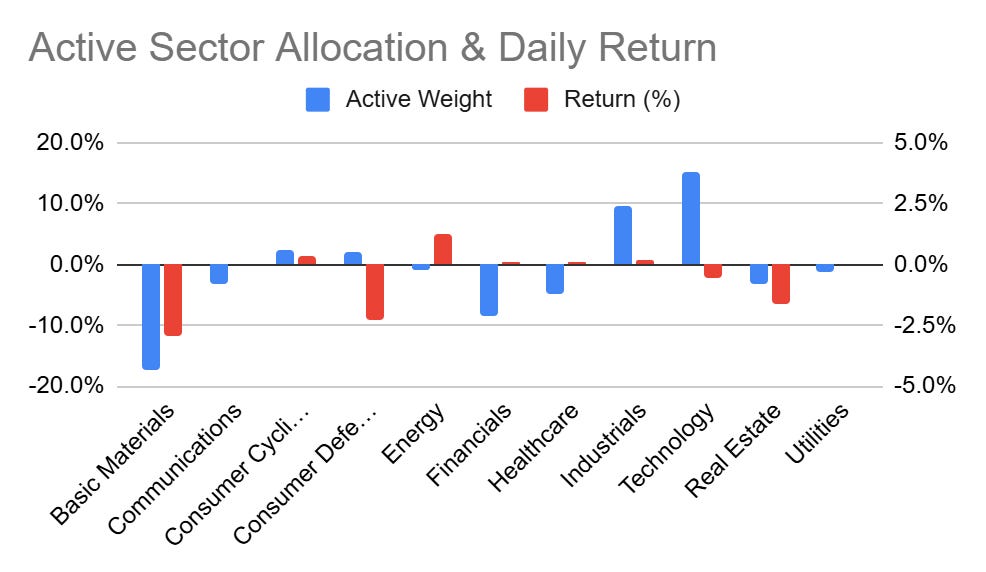
Most markets ended overnight down, in particular the KOSPI fell -5.5% led by falls in SK Hynix and Samsung. Small caps (Russell 2000) are clearly having a worse time than large caps (S&P500). Energy (+1.74%) remains the leading sector driven by higher oil prices, while Healthcare (-1.33%) lag. We are in an interesting market cycle whereby growth indicators (like ISM PMIs) are supportive amid headline inflation increasing. All eyes will be on the US September CPI tonight. Consensus estimates headline of 3.6% y/y.

Australian Market
The ASX finished the day down -0.64%, the worst sectors being Financials (-1.41%) and Materials (-0.88%). Evolution Mining fell short on their gold production estimates which sent the stock down -3.16%. A bright spark in the sector was PLS, lithium, up +2.92%. Financials were down across the board with all the majors suffering share price losses. Consumer credit appears to be the exception here, with ZIP (+4.25%) and EML (+10%) posting gains. Glencore made its ASX debut. This just adds a secondary listing to the primary on the LSE.
Portfolio Commentary
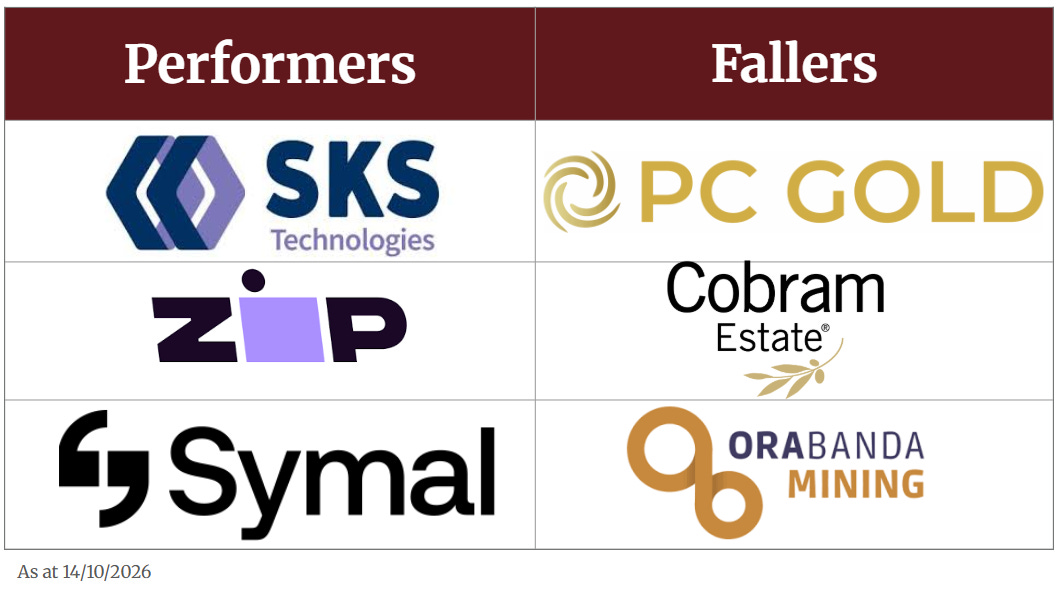
The portfolio fell -0.40%, outperforming the ASX 300 benchmark (-0.64%). This was driven by the tech, and industrial names. Gains in Zip (+4.25%), SKS (+7.98%), C79 (+2.49%), and SYL (+2.69%), supported the portfolio. Meanwhile, PC2 (-6.25%), CBO (-4.51%), and OBM (-2.50%), dragged the portfolio. Pleasingly, Megaport (-1.92%) only had a minor fall, most likely due to Goldman rating the stock a “Buy”. They provide a target price of $25.90 (31% upside).
Investment Activity
None
Disclaimer: This is a paper portfolio. Content is for educational purposes only and does not constitute financial advice. Always do your own research.