
Fund Status:
Portfolio Val: $1,079,096
Performance : Portfolio 1.27% | Benchmark 0.01%
MTD : Portfolio -3.76% | Benchmark 0.46%
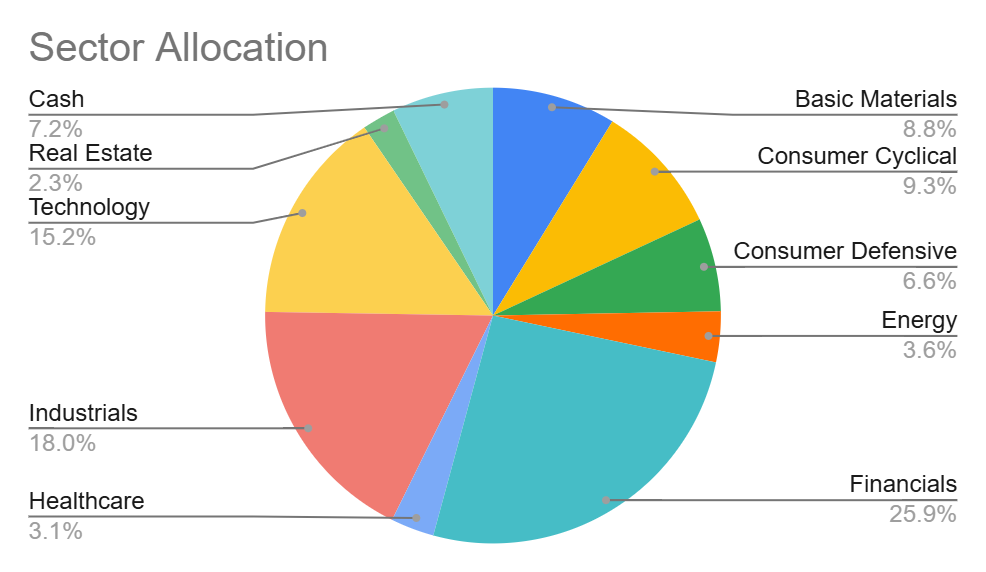
Cash: $77,724
Bought/Sold JDO, MVF, NWL, SKS / None
Overnight Markets
Markets were up overnight with the S&P up +0.77% but it was the NASDAQ and the Russell who were the standouts, rallying more than 1% each. Sector wise, Technology was up +1.49% while Energy slipped -2.20% as oil fell below $100. Interestingly, Software lost ground (-0.15%) while Semis and Semiconductor Equipment jumped +2.37% in anticipation of Anthropic’s IPO. All eyes are on reporting season as investors parse through the updates.
A company that you would be surprised has exposure to the AI and DC trade is UPS, the package delivery service. DC builders need materials, which UPS delivers and or stores for clients, as well as components for servers, which is predicted to be a recurring revenue stream as servers need refurbishment (new chips) regularly.
Microsoft and Google are due to report overnight with Bloomberg estimates forecasting revenues at $90.63B and $111.24B respectively. The market will pay particular attention to Microsoft’s Azure to judge the strength of their cloud business. Revised financial reporting should make it easier to compare Azure revenue figures, cloud growth, and capex spending.

Australian Market
Top news today was inflation coming in higher than expectations. Trimmed mean CPI was only slightly higher by 0.1% to 3.6%, but more is more. RBA Governor Michelle Bullock stated that subdued economic growth is needed to bring inflation down, while Shadow Treasury Tim Wilson blames (unsurprisingly) current government spending on inflation. The market, while it did drop broadly at 11:30am, remained robust with most of the movements following the performance of the US market the night before.
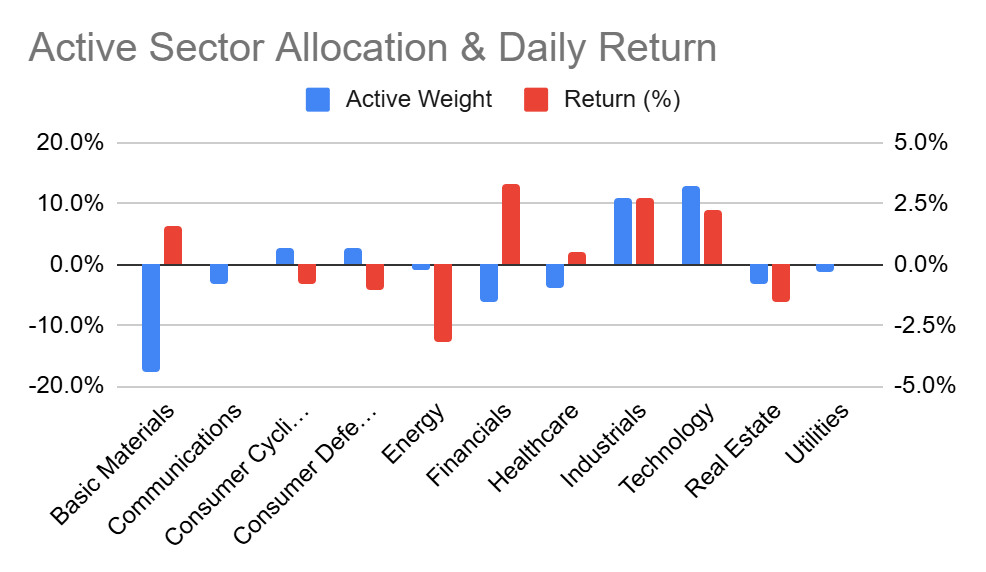
The ASX200 finished the day flat (-0.03%) as the mix of sector performances evened out; Tech (+2.36%) and Materials (+1.07%) were the only real leaders while all other sectors went lower. Energy (-2.45%) and Discretionary (-1.53%) suffering in particular due to oil names (WDS, STO, ALD) and lower expected consumer spending from higher rates (WES, ALL, TLC).
Portfolio Commentary
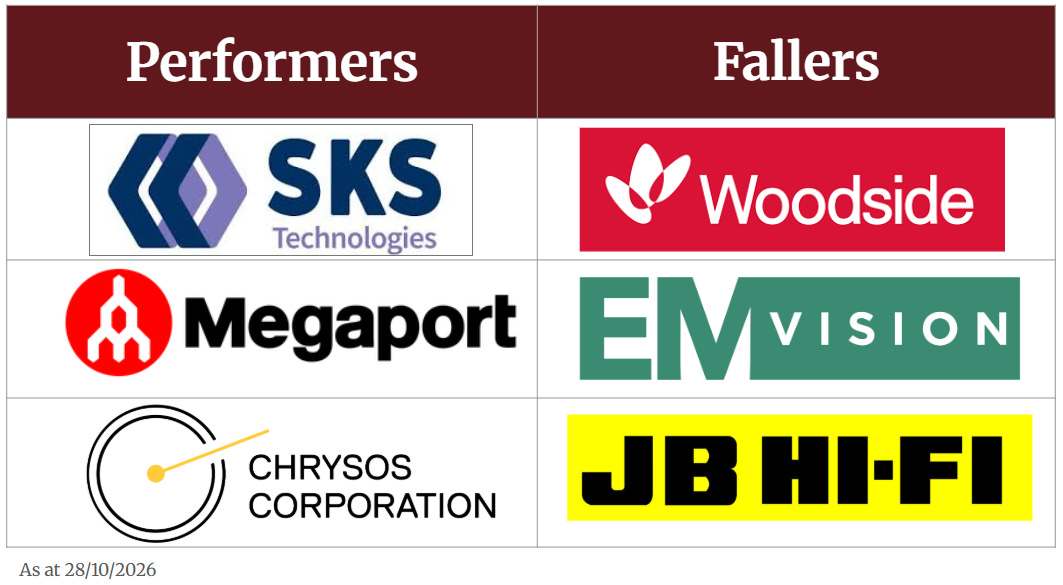
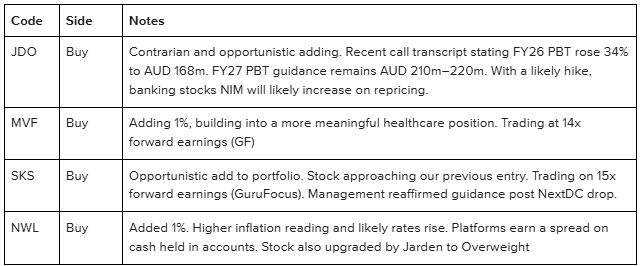
The portfolio had a strong recovery today +1.27% against a flat ASX300 benchmark (+0.01%). Performance was driven by a risk-on rally across tech and financials. Namely, SKS (+6.34%), Megaport (+5.12%), C79 (+4.35%), GDG (+4.23%), NWL (+4.00%), and HMC (+3.89%). On the trading front, we made four targeted additions: opportunistically buying Judo, SKS, Netwealth, and Monash IVF. Our good performers covered the softer energy and retail names, Woodside (-3.16%), EMV (-2.91%), JBH ( -2.30%), and Coles (-1.21%). Cash now sits at 7.2%.
Investment Activity
Disclaimer: This is a paper portfolio. Content is for educational purposes only and does not constitute financial advice. Always do your own research.