
We are getting on the front foot, posting our performance for September 2026 early so that Paper Mandate can get back to regularly posting portfolio updates.
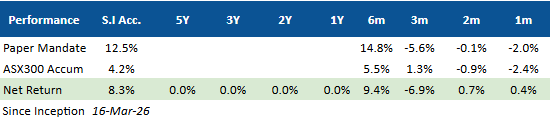
We are happy with the performance of the portfolio despite being down in September -2.01%, as it outperformed the S&P/ASX 300 Accumulation Index by +0.42%, which posted a loss of -2.43%.
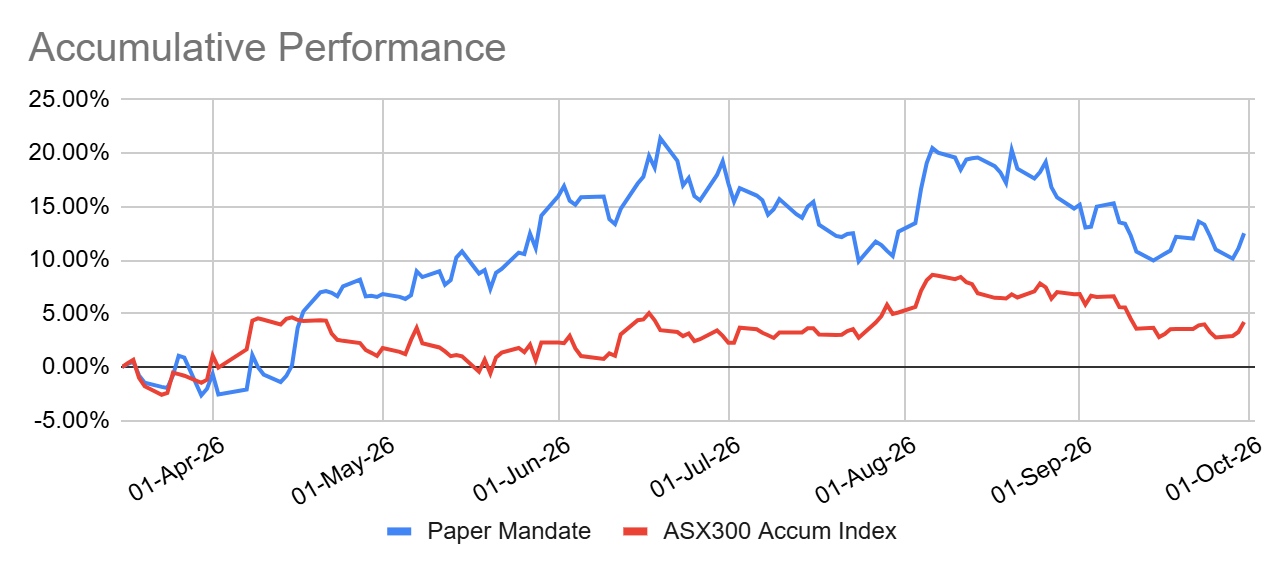
Our track record since inception is still outperforming the benchmark with an accumulative return of 12.5% versus 4.2%, a +8.3% net outperformance.
The main drivers of returns were rallies in SKS, MP1, and CCL. The rest of the portfolio was dragged due to higher rates, a higher inflation print, and higher input costs (driven by the US/Iran war).
Portfolio Attribution
The portfolio’s monthly return was driven primarily by the Interaction Effect (+2.20%), while Allocation and Stock Effect (-0.51% & -1.28%) were overall detractors.
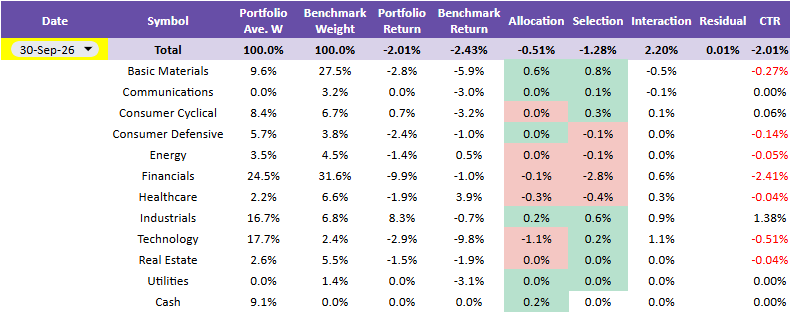
Most of our sectors had positive selection contribution, meaning most of the individual stocks performed better than their overall sector.
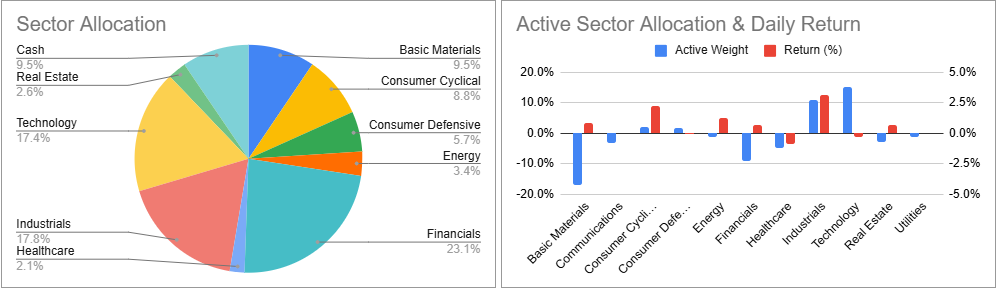
The portfolio’s Technology exposure outperformed the benchmark’s sector return, but drove a negative Allocation Effect (-1.1%) as we had a large overweight (+17.7% vs 2.3%) in the portfolio. Thankfully, the stocks held up in a down market which contributed to the positive Selection and Interaction Effect.
Industrials were the best positive contributors to performance (+1.38%), driven by SKS rallying +30.6%. Now SKS is considered an Industrial by Commsec and other outlets. If we change this Technology, the CTR for the sector improves.
Financials was the largest detractor to the portfolio, especially seeing the Selection Effect (-2.8%) and CTR (-2.41%). While the Benchmark sector fell -1.0%, our Financials were more impacted by the rates move, falling -9.9%. NWL, ZIP and GDG are all particular interest rate sensitive.
Pleasingly, the Residual in the Attribution table was negligible, +0.01%
Key Contributors & Detractors
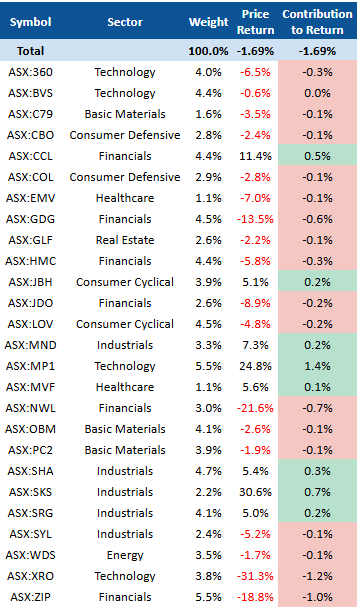
The NAV decreased -2.01% during August. The specific positions that drove the return by contribution were:
Megaport (MP1): Rose +24.8% and contributing +1.4% to total return
SKS Technologies (SKS): Up +30.6%, adding +0.7% to portfolio return.
Cuscal (CCL): Advanced +11.4%, contributing +0.5%.
Key detractors were:
Xero (XRO): Fell -31.3%, detracting -1.2%
Zip Ltd (ZIP): Dropped -18.8%, detracting -1.0% to total return.
Netwealth (NWL): Declined -21.6%, detracting -0.7% from total return
Portfolio Characteristics & Risk Metrics
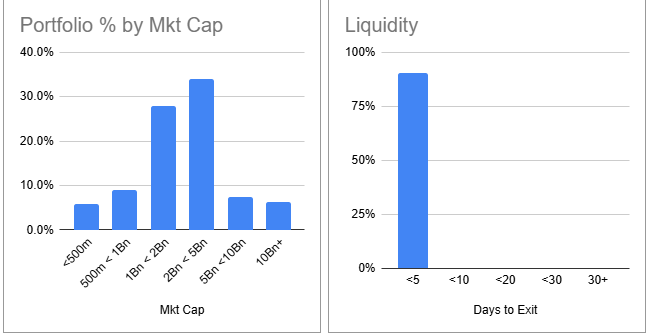
The current profile favours the mid-cap sweet spot, with the majority of companies between $1Bn to $5Bn in market cap.
The portfolio liquidity remains the same. Considering a 30% Average Daily Volume (ADV), the portfolio has a Days to Exit of 5 days. This is due to the small FUM size.
Other statistics include:
Weighted Avg Mkt Cap: $4,571m, lower than last month.
WA Beta (1Y): 1.16, down from 1.20 indicating a less sensitive portfolio.
WA P/E Ratio: 28.4x, down from last month
Our Beta sensitivity is still a concern as this will make the performance of the portfolio swing session to session.
The largest contributor to the Weighted Average PE is C79, with a current PE of 437x. This is last twelve months EPS mind you. Forward estimates make the PE much lower, 72x.
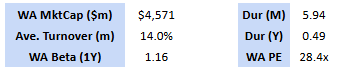
At the end of the month, the largest overweight is still Technology (+15.2% ) while Materials continues to be the largest underweight (-17.0%).
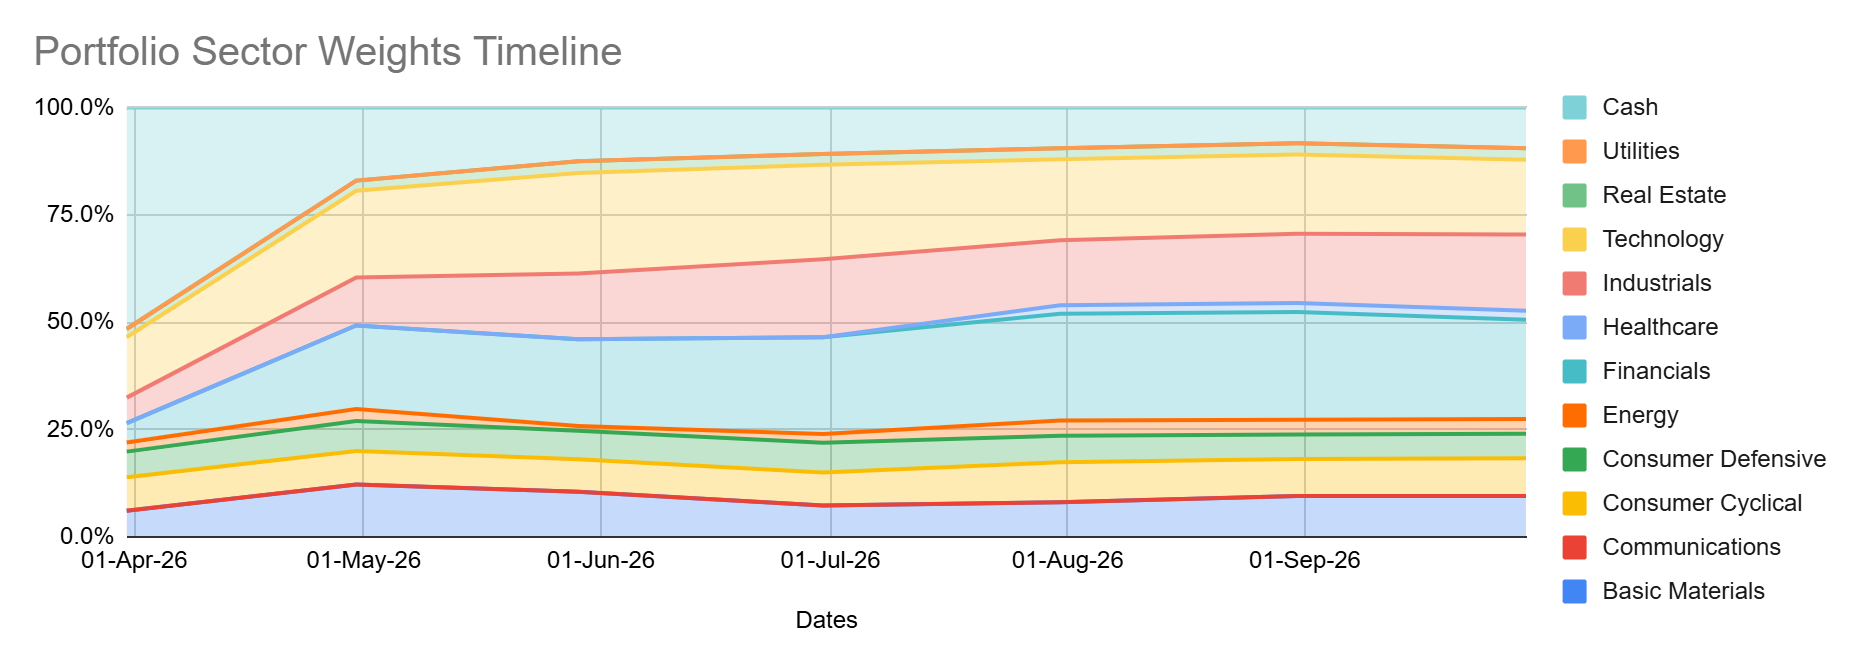
There were no large wholesale changes to the portfolio. We sold 1% of MP1 before month-end.
Outlook & Strategy
This was an okay month, outperforming the benchmark, despite not changing the portfolio. The portfolio has generated a 12.5% absolute return since inception.
The AI theme and sentiment remains cautious. At time of writing, we trimmed our exposure to MP1. It is likely further trims to Technology are on the cards. The war in Iran, higher input costs, sticky inflation, and interest rates are a drag for equities. Being fully invested may be a risk to the portfolio.
The focus for the coming months will be to strategically take profits, and invest in areas that are undervalued. Australia is likely at the end or near end of the hiking cycle, so Consumer Discretionary names have are likely near full a derate. This is to keep our contrarian philosophy and not follow the trends.
Disclaimer: This is a paper portfolio. Content is for educational purposes only and does not constitute financial advice. Always do your own research.