
Since our last update, we were down for the month but were making a recovery to lessen the impact for the month. By 22nd October, the Month to Date underperformance to the index had narrowed to -3.38% (not great but manageable).
Unfortunately, one bad day can ruin best laid plans. 23th October saw red across the board. Not to mention the 30% drop in ZIP. This has increased the underperformance of the fund for the month.
We will do a deeper attribution analysis come month end however, this is a good reminder that position sizing is important. However, as we have a contrarian philosophy, we should a) expect drawdowns but b) (more importantly) view this as an opportunity to take advantage of market dislocation. This is indeed why we are holding more cash.
Fund Status:
Portfolio Val: $1,049,783
Performance : Portfolio 0.47% | Benchmark 0.18%
MTD : Portfolio -6.38% | Benchmark -0.05%
Cash: $131,705
Bought/Sold COL / MP1, BVS
Overnight Markets
Friday had a shocking ending to the week in markets. It didn’t matter if you were large (S&P500) or small (Russell), stocks were down. The only sector leading the way was Energy, driven by the eye-watering cost of oil. Brent crude was up $116.72 per barrel. Other sectors were down in the dumps. Post the PHP vulnerability, CrowdStrike, Palo Alto and Cloudflare were up. Software (IGV) outperformed Semis (SOXX) and, at time of writing, SOXX is down -14% for the month.

Australian Market
The ASX 200 finished up (+0.17%) with Material (+1.71%), and Real Estate (+1.32%) leading while Staples (--1.54%) and Discretionary (-0.96%) lagged. Big retailers like Woolworths, Coles and Endeavour dragged down Staple while Wesfarmers and the gambling stock (LNW, ALL, TLC) pulled down Discretionary. Meanwhile, most of the big miners held up the index and Materials. Zip had a recovery after brokers stated, in their opinion, the fraud incident and higher bad debts were temporary. They also pointed out the supportive US growth to credit.
Portfolio Commentary
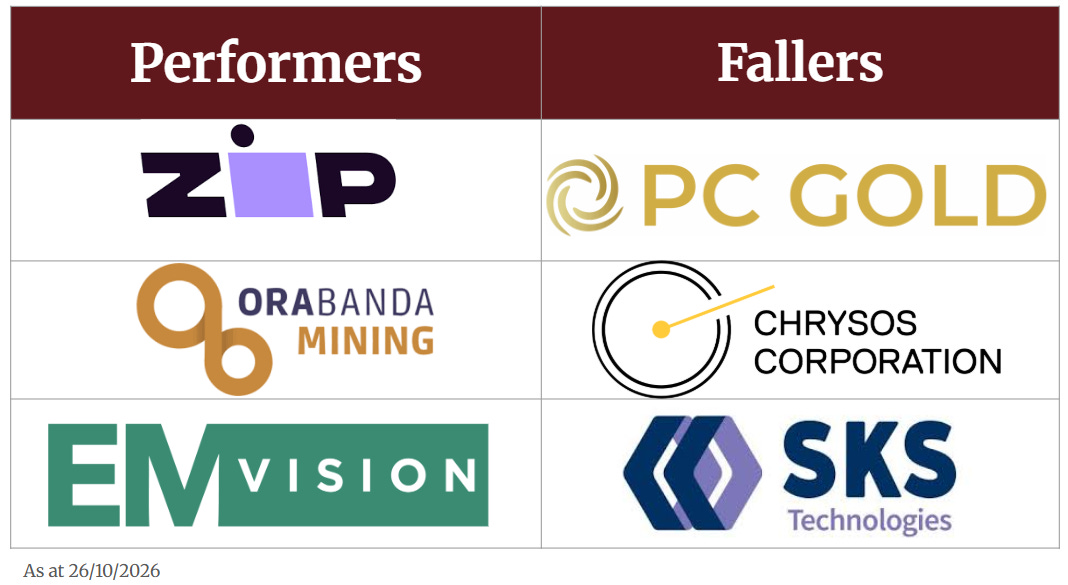
The portfolio rose +0.47%, outperforming the ASX 300 benchmark (+0.18%). ZIP’s recovery (+11%) from Friday’s -30% is certainly a welcomed relief. Plus we saw some nice rallies in Ora Banda (+6.76%), EMV (+4.45%), and Bravura (ASX: BVS, +3.37%). Unfortunately our smaller companies are struggling in this environment, namely, PC2 (-4.44%), C79 ( -4.20%), and SKS (-3.72%). We have not had a chance to adjust the portfolio in a while but today we found time and took the opportunity to take some profits on winning positions (MP1, BVS) and top up on Coles. Inflation is forecasted to be stable (so elevated) and being in a large cap staples company should provide protection. Cash reserves have risen to 12.5%. We will use this dry powder to add to higher conviction names.
Investment Activity

Disclaimer: This is a paper portfolio. Content is for educational purposes only and does not constitute financial advice. Always do your own research.