

After just getting out the performance report for September it has been a busy couple of weeks. Let’s summarize from 30th September to now.
Our Gross Asset Value (GAV) decreased from $1,121,268 to $1,096,240 (a net change of -2.23%).
The benchmark by comparison has returned -0.24% month to date.
We initially had good performance from Industrials and Technology at the start of the month. But there has since been a pullback led by the falls in software and semis related stocks (MP1, SKS)
Fund Status:
Portfolio Val: $1,096,240
Returns MTD: Portfolio -2.33% | Benchmark -0.24%
Cash: $106,576
Bought/Sold None
Market Commentary
It has been a brutal couple of weeks markets wise. Global markets over the first half of October have continued to grapple with escalating Middle East conflict risks, surging energy inputs, and persistent inflationary pressures that have forced central banks to maintain a hawkish stance.
Australian business sentiment hit a wall, with both the NAB Business Confidence Index and the Westpac Consumer Sentiment plummeting into the negative. Domestic tech and AI infrastructure suffered a sharp reality check after Firmus pulled its IPO. Hope you had a bowl of popcorn while watching the fireworks. Who would have thought that a loss-making, debt heavy, over promising, overvalued, and over hyped and company, with a string of IOUs from AI companies would have imploded…?
OpenAI, and Anthropic also delayed their IPOs on concerns of AI capex spending becoming tougher to justify.
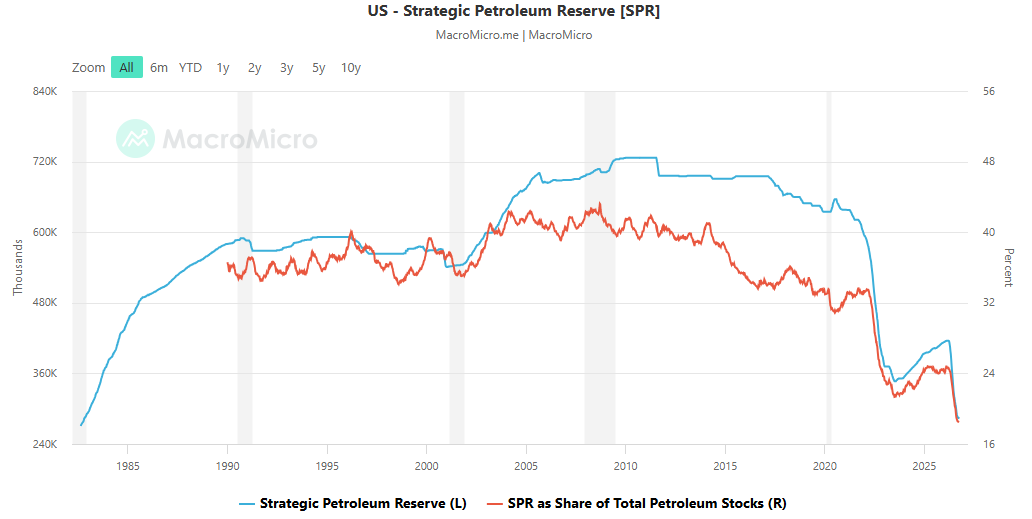
Energy meanwhile has been the bright spark as oil remains above $100 per barrel. Even though the US has stated it will not attack Iran until after midterms (how considerate…), the US recently offered up 40m barrels from the SPR and encouraged other countries to do the same. Now the SPR is at its lowest level in 40+ years.
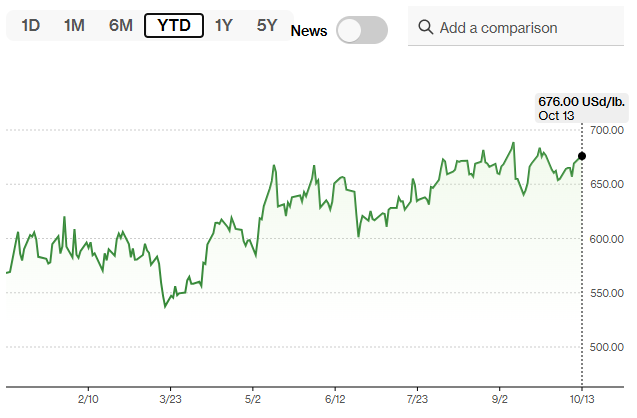
In other commodity news, copper remains at its near record levels. Low inventories and a tight market are supporting the price.
EOD Australian Market 13/10/2026
The ASX 200 finished flat today (+0.01%), anchored by a late session rally in the major banks led by CBA (+2.3%) offset by selling across Tech (-4.37%) and Materials (-2.03%). Energy (+1.2%) continued to gain on oil related names (Santos +1.60%). There was also a wave of selling across lithium names (PLS Group -8.6%) on European import cap concerns. Notably, sentiment across AI infrastructure names deteriorated sharply after reports that AirTrunk will be delaying its Singapore REIT IPO. SKS (-20.5%) and MP1 (-9.9%) sold off on the news. This was late in the day.
Disclaimer: This is a paper portfolio. Content is for educational purposes only and does not constitute financial advice. Always do your own research.